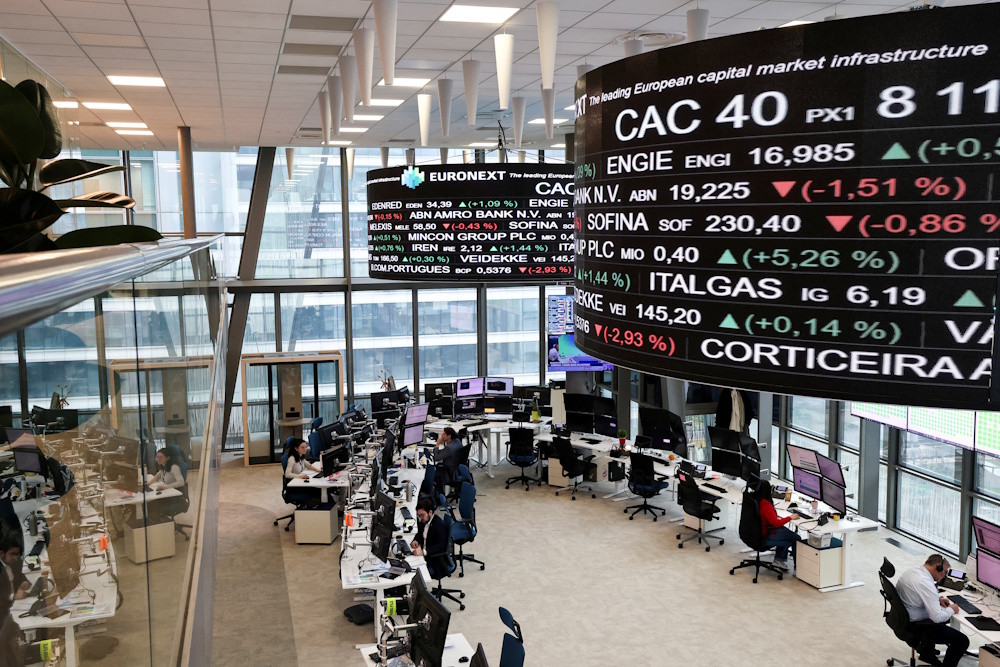
French stocks relinquished early gains, dipping slightly below the flat line on Wednesday as sentiment shifted to a more cautious stance, despite preliminary survey data from S&P Global indicating robust private sector activity for the month of September. The firm started this morning with robust economic data alongside a significant decline in oil prices. Brent crude prices declined to $97.91 a barrel as apprehensions regarding global oil supplies have lessened. Investors responded to reports indicating that Iran may be prepared to reopen the Strait of Hormuz within a week, contingent upon the United States alleviating military pressure and removing its blockade on Iranian ports.
Additionally, reports indicate that Saudi Arabia has restarted its East-West oil pipeline and is preparing to resume Red Sea oil exports from Yanbu. However, stocks weakened as the session progressed, following a recovery in oil prices from the day’s lows, which managed to rise above the flat line. Brent crude futures were at $99.60 a barrel recently, reflecting an increase of approximately 0.35%. The benchmark CAC 40, which advanced to 8,199.66 earlier in the session, was down 5.19 points or 0.06% at 8,149.72 at noon.
- Kering experienced a decline of nearly 2%.
- Orange experienced a decline of approximately 1.6%, whereas Stellantis, Sanofi, Unibail Rodamco, Eiffage, and STMicroelectronics saw losses ranging from 1% to 1.25%.
- L’Oreal, Pernod Ricard, Bureau Veritas, Vinci, Renault, Eurofins Scientific, Bouygues, and Capgemini exhibited a decline as well.
- Societe Generale experienced an increase of 1.85%.
- Euronext gained approximately 1.2%, with Safran, Credit Agricole, Publicis Groupe, Air Liquide, BNP Paribas, EssilorLuxottica, Engie, Legrand, and Carrefour recording modest increases.
Data from indicated that France’s private sector activity experienced a resurgence in September, achieving the most rapid growth observed in over two years. The headline composite output index recorded a value of 51.2 in September, an increase from 48.5 in August. The private sector activity concluded the period of contraction that began at the start of the year. Moreover, the reading indicated the most robust growth since August 2024. The services Purchasing Managers’ Index reached a 10-month peak of 51.4, an increase from 48.0 in August. Meanwhile, the factory PMI decreased to 50.3 from 51.1. Eurozone’s September Flash Composite PMI reading registered at 53.1, an increase from August’s figure of 52.0. The PMI reading was anticipated to be at 51.7.